Where, Oh Where Are Millennials Buying Homes?

By Susanne Dwyer

millenial_buying_homes_1_map

We know that millennials aren’t entering the housing market at the rate their parents did. Between student loan debts and rising home prices, some have understandably cold feet—so cold that homeownership rates for those under 35 dropped from 40 percent in 2006 to 32 percent in 2015. Despite this, some millennials are still battling the sky-high rental market by becoming homeowners. The question is, where?

In its second annual study, SmartAsset looked at data on under-35 homeownership rates in the 200 largest U.S. cities to identify where millennials are buying homes. Below are a handful of the hottest highlights:

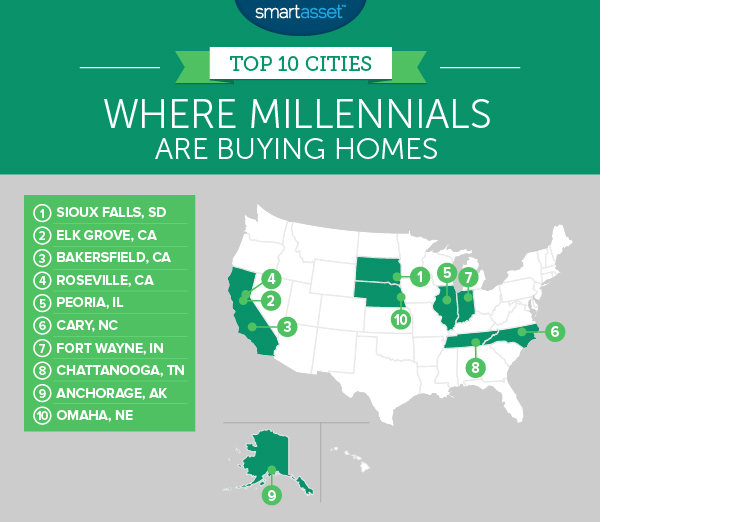
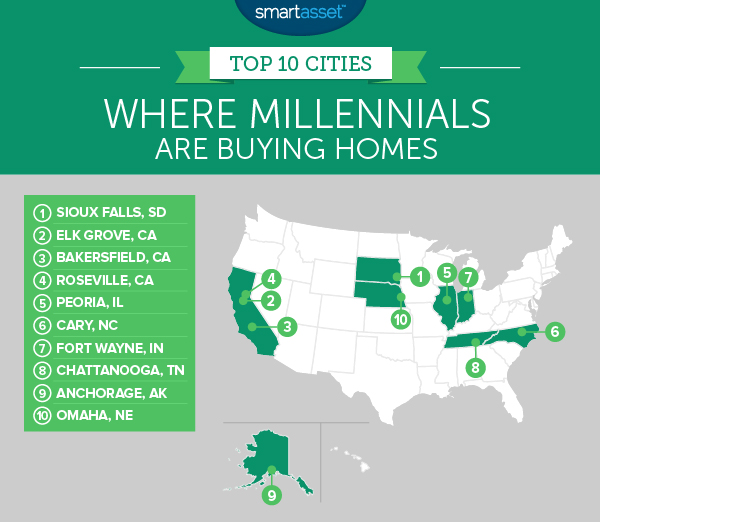
Location matters. When looking at locations, the variance in homeownership for millennials is huge. In Elk Grove, Calif., for instance, millennial homeownership tops at 61 percent, while New Haven, Conn. locks in a measly 5 percent.

Sacramento steals. Two smaller cities in the Sacramento Metro Area ranked in the top 5 places where millennials are buying homes, perhaps attributable to Sacramento’s strong STEM job market.

All hail Illinois? Peoria, Ill. is becoming popular. From 2006-2015, Peoria’s under-35 homeownership rate jumped 8 percent, the highest increase in the SmartAsset study.

Northeast falls behind. Springfield, Mass. is the only Northeast city to crack the top 25. Cities in this region tend to rank lower on the list.

So where exactly are millennials buying? Here’s a fun little infographic to break it down for ya.

Source: SmartAsset

Zoe Eisenberg is RISMedia’s senior content editor. Email her your real estate news ideas at zoe@rismedia.com.

This was originally published on RISMedia’s blog, Housecall. Visit the blog daily for housing and real estate tips and trends. Like Housecall on Facebook and follow @HousecallBlog on Twitter.

The post Where, Oh Where Are Millennials Buying Homes? appeared first on RISMedia.

…read more

From:: Real Estate News

Real Estate Leaders Identify Pivotal Business Challenges for 2017

By Beth McGuire

Study Shows the Continued Struggle to Stay Competitive and Relevant in the Changing Economy

As they grow less confident in the economy, top real estate executives at firms of all sizes find themselves united by a key concern for 2017: Agent recruitment and retention.

In the latest Imprev Thought Leader survey, 85 percent of participants agree that recruiting more agents is their most critical business challenge. The challenge continues when it comes to reaching younger agents; over 52 percent ranked “attracting younger agents” among their top concerns.

A broker/owner of a major franchise office in Minnesota gives depth to his recruiting worries: “Recruiting is and always has been our biggest challenge. While we continue to grow, it’s never at the pace we want it to be. While recruiting younger, less-experienced agents has improved for us this year, we’ve noticed increased difficulty in recruiting the top talent.”

Many boutique firms are also worried about the competition for talent. In Southern California, a leader of a smaller brokerage laments that her top recruiting challenge is “being able to offer agents alternative motivation to stay or join our firm. We are a family-run boutique business and cannot compete with the money of the heavily-backed firms.”

Agent productivity is also top of mind for the top real estate executives and broker/owners surveyed. Forty-four percent of participants rank “getting agents to use broker-provided technology” as their next critical business concern—beating out lead generation (34 percent) and lead follow-up (36 percent). A broker/owner in California struggles to get “user adoption of tools that will help agents communicate with their clients,” while a Dallas-area broker/owner says, “We feel confident in our technology we have in place; we need to continue to teach and train for this technology.”

When it comes to technology, leaders face a myriad of challenges. More than half of survey respondents rank “getting our systems to work together” as their most critical technology challenge for 2017. It’s a struggle to have “technology that is cohesive,” says a broker/owner at a top Southwestern Florida brokerage. Better technology integration isn’t their only worry. Leaders said having “systems for more effectively competing against the RE portals for generating leads” (44 percent) and “increasing mobile capabilities for agents” (36 percent) are their next pressing concerns. A Houston, Texas broker running a major franchise office shares his goal of seeing “seamless integration of the transaction, from agent to corporate to closing, and simplified use of mobile devices to enter all data across the company,” while the leader of smaller Florida brokerage notes her battle is to “stay on top of technology to compete with bigger brokers.”

“Real estate leaders clearly believe that the technology they provide to their agents is widely underused,” says Renwick Congdon, chief executive officer of Imprev. “So how does the industry begin to improve agent adoption? By reducing complexity. Systems need to seamlessly fit into the agent’s business and process. Integrated and connected platforms—rather than ‘apps’ and standalone solutions—are imperative to successfully compete with the portals.”

Beautifully summing up the struggle to stay …read more

From:: Finance and Economy

Real Estate Leaders Identify Pivotal Business Challenges for 2017

By Beth McGuire

Study Shows the Continued Struggle to Stay Competitive and Relevant in the Changing Economy

As they grow less confident in the economy, top real estate executives at firms of all sizes find themselves united by a key concern for 2017: Agent recruitment and retention.

In the latest Imprev Thought Leader survey, 85 percent of participants agree that recruiting more agents is their most critical business challenge. The challenge continues when it comes to reaching younger agents; over 52 percent ranked “attracting younger agents” among their top concerns.

A broker/owner of a major franchise office in Minnesota gives depth to his recruiting worries: “Recruiting is and always has been our biggest challenge. While we continue to grow, it’s never at the pace we want it to be. While recruiting younger, less-experienced agents has improved for us this year, we’ve noticed increased difficulty in recruiting the top talent.”

Many boutique firms are also worried about the competition for talent. In Southern California, a leader of a smaller brokerage laments that her top recruiting challenge is “being able to offer agents alternative motivation to stay or join our firm. We are a family-run boutique business and cannot compete with the money of the heavily-backed firms.”

Agent productivity is also top of mind for the top real estate executives and broker/owners surveyed. Forty-four percent of participants rank “getting agents to use broker-provided technology” as their next critical business concern—beating out lead generation (34 percent) and lead follow-up (36 percent). A broker/owner in California struggles to get “user adoption of tools that will help agents communicate with their clients,” while a Dallas-area broker/owner says, “We feel confident in our technology we have in place; we need to continue to teach and train for this technology.”

When it comes to technology, leaders face a myriad of challenges. More than half of survey respondents rank “getting our systems to work together” as their most critical technology challenge for 2017. It’s a struggle to have “technology that is cohesive,” says a broker/owner at a top Southwestern Florida brokerage. Better technology integration isn’t their only worry. Leaders said having “systems for more effectively competing against the RE portals for generating leads” (44 percent) and “increasing mobile capabilities for agents” (36 percent) are their next pressing concerns. A Houston, Texas broker running a major franchise office shares his goal of seeing “seamless integration of the transaction, from agent to corporate to closing, and simplified use of mobile devices to enter all data across the company,” while the leader of smaller Florida brokerage notes her battle is to “stay on top of technology to compete with bigger brokers.”

“Real estate leaders clearly believe that the technology they provide to their agents is widely underused,” says Renwick Congdon, chief executive officer of Imprev. “So how does the industry begin to improve agent adoption? By reducing complexity. Systems need to seamlessly fit into the agent’s business and process. Integrated and connected platforms—rather than ‘apps’ and standalone solutions—are imperative to successfully compete with the portals.”

Beautifully summing up the struggle to stay …read more

From:: Real Estate News

Square Footage Shrinks in Response to First-Time Homebuyers

By Susanne Dwyer

The average home built in 2016 was 2,634 square feet, smaller than homes built the year prior, per recent data by the U.S. Census Bureau. The downsize, according to the National Association of Home Builders (NAHB), is in response to first-time homebuyers.

“The data on new home characteristics show a pattern,” says Rose Quint, assistant vice president for Survey Research at the NAHB. “2016 marked the end of an era that began in 2009 when homes got bigger and bigger with more amenities. I expect the size of homes to continue to decline as demand increases from first-time buyers.”

The NAHB’s recent Home Builder Preferences Survey reveals that in addition to closer quarters, new homes are now being constructed with separate laundry rooms, which are in-demand by both first-time homebuyers and other generations of buyers. Energy-efficient add-ons are also a top preference, as well as a main floor full bathroom. Features on their way out include cork flooring, an outdoor kitchen and a pet washing station.

The penchant for shrunk-down square footage, however, seems to vary by income. According to the survey, the more income the homebuyer earns, the more space they seek, with homebuyers earning $150,000 or more annually preferring a 2,500-square-foot home.

Source: National Association of Home Builders (NAHB)

The post Square Footage Shrinks in Response to First-Time Homebuyers appeared first on RISMedia.

…read more

From:: Finance and Economy

Square Footage Shrinks in Response to First-Time Homebuyers

By Susanne Dwyer

The average home built in 2016 was 2,634 square feet, smaller than homes built the year prior, per recent data by the U.S. Census Bureau. The downsize, according to the National Association of Home Builders (NAHB), is in response to first-time homebuyers.

“The data on new home characteristics show a pattern,” says Rose Quint, assistant vice president for Survey Research at the NAHB. “2016 marked the end of an era that began in 2009 when homes got bigger and bigger with more amenities. I expect the size of homes to continue to decline as demand increases from first-time buyers.”

The NAHB’s recent Home Builder Preferences Survey reveals that in addition to closer quarters, new homes are now being constructed with separate laundry rooms, which are in-demand by both first-time homebuyers and other generations of buyers. Energy-efficient add-ons are also a top preference, as well as a main floor full bathroom. Features on their way out include cork flooring, an outdoor kitchen and a pet washing station.

The penchant for shrunk-down square footage, however, seems to vary by income. According to the survey, the more income the homebuyer earns, the more space they seek, with homebuyers earning $150,000 or more annually preferring a 2,500-square-foot home.

Source: National Association of Home Builders (NAHB)

The post Square Footage Shrinks in Response to First-Time Homebuyers appeared first on RISMedia.

…read more

From:: Real Estate News

MBA: Mortgage Apps Rise, Refis Fall

By Susanne Dwyer

Mortgage applications rose 5.8 percent over the week, according to data gathered in the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey. The MBA’s Refinance Index grew 4 percent, as well, while the Purchase Index grew 45 percent.

The refinance share of mortgage activity, however, decreased to 51.2 percent of total applications from 52.2 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 5.5 percent of total applications.

The FHA share of total applications also increased to 11.7 percent from 11.6 percent the previous week, while the VA share of total applications increased to 12.8 percent from 12.3 percent the previous week. The USDA share of total applications decreased to 0.9 percent from 1.1 percent the previous week.

According to data from the survey, the average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($417,000 or less) decreased to 4.32 percent from 4.39 percent, with points decreasing to 0.41 from 0.43 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $417,000) decreased to 4.27 percent from 4.37 percent, with points decreasing to 0.31 from 0.44 (including the origination fee) for 80 percent LTV loans. The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 4.08 percent from 4.22 percent, with points increasing to 0.35 from 0.34 (including the origination fee) for 80 percent LTV loans.

The average contract interest rate for 15-year fixed-rate mortgages, in addition, decreased to 3.56 percent from 3.64 percent, with points increasing to 0.42 from 0.38 (including the origination fee) for 80 percent LTV loans. The average contract interest rate for 5/1 ARMs increased to 3.32 percent from 3.28 percent, with points increasing to 0.46 from 0.42 (including the origination fee) for 80 percent LTV loans.

Source: Mortgage Bankers Association (MBA)

The post MBA: Mortgage Apps Rise, Refis Fall appeared first on RISMedia.

…read more

From:: Finance and Economy

MBA: Mortgage Apps Rise, Refis Fall

By Susanne Dwyer

Mortgage applications rose 5.8 percent over the week, according to data gathered in the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey. The MBA’s Refinance Index grew 4 percent, as well, while the Purchase Index grew 45 percent.

The refinance share of mortgage activity, however, decreased to 51.2 percent of total applications from 52.2 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 5.5 percent of total applications.

The FHA share of total applications also increased to 11.7 percent from 11.6 percent the previous week, while the VA share of total applications increased to 12.8 percent from 12.3 percent the previous week. The USDA share of total applications decreased to 0.9 percent from 1.1 percent the previous week.

According to data from the survey, the average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($417,000 or less) decreased to 4.32 percent from 4.39 percent, with points decreasing to 0.41 from 0.43 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $417,000) decreased to 4.27 percent from 4.37 percent, with points decreasing to 0.31 from 0.44 (including the origination fee) for 80 percent LTV loans. The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 4.08 percent from 4.22 percent, with points increasing to 0.35 from 0.34 (including the origination fee) for 80 percent LTV loans.

The average contract interest rate for 15-year fixed-rate mortgages, in addition, decreased to 3.56 percent from 3.64 percent, with points increasing to 0.42 from 0.38 (including the origination fee) for 80 percent LTV loans. The average contract interest rate for 5/1 ARMs increased to 3.32 percent from 3.28 percent, with points increasing to 0.46 from 0.42 (including the origination fee) for 80 percent LTV loans.

Source: Mortgage Bankers Association (MBA)

The post MBA: Mortgage Apps Rise, Refis Fall appeared first on RISMedia.

…read more

From:: Real Estate News

Even High Earners Struggle to Save

By Susanne Dwyer

A considerable percentage of Americans lack the savings needed to cushion against a surprise expense, even with enough income to save, according to a recent report by Bankrate.com. Approximately 60 percent of those surveyed do not have enough savings for a $1,000 emergency room bill, though 41 percent plan to tap their savings for such an expense.

“It’s not a matter of if, but when an unexpected expense will pop up,” said Jill Cornfield, Bankrate.com analyst, in a statement. “Our survey shows that just under half of adults surveyed said they or a family member had a major expense in the past 12 months.”

Half of high-income households do not have adequate savings, according to the report, despite having the financial wherewithal to support saving. Millennials have more savings stashed for an unforeseen bill than any other generation, at 47 percent of those surveyed.

The struggle to save is underscored by the “luxuries” Americans are willing to let go of—and the ones they aren’t. Fifty-nine percent of those surveyed would trim dining out from their budgets, but just 35 percent would cut their cell phone plan.

“If you have a car, a house or apartment, a pet, or a kid—if you’re a member of the human race—something that costs money is bound to go wrong,” said Cornfield. “It might be a minor car repair or a surprise medical expense. The best way to prepare is to have an emergency fund you can draw on.”

Source: Bankrate.com

For the latest real estate news and trends, bookmark RISMedia.com.

The post Even High Earners Struggle to Save appeared first on RISMedia.

…read more

From:: Real Estate News

MSRs Being Auctioned on $1.4 Billion in GSE Loans

A bulk offering of mortgage-servicing rights on government-sponsored enterprise originations includes rights on more than $1.4 billion in loans.

MSRs on Fannie Mae and Freddie Mac mortgages with an aggregate outstanding principal balance of $1.45 billion are being offered for sale.

A majority of the loans were originated through the retail channel. Properties securing two-thirds of the loans are in Texas and Colorado.


…read more

From:: Financing

Falling Rates Drive Up Mortgage Refinance Biz

A recent decline in mortgage rates has driven up demand from borrowers who missed out on the last refinance opportunity, though home buyers were also busier.

The U.S Mortgage Market Index from OpenClose and Mortgage Daily was 131 in the week that concluded on Jan. 13. There are no seasonal adjustments.

It was the best showing for the index — a reflection of rate lock volume by OpenClose users — since the week that ended on Dec. 16, 2016, when it was 154.


…read more

From:: Financing